Partners Group did not run out of cash this quarter. It ran out of the ability to pretend that its stated net asset value and the price at which investors can actually leave are the same figure. That is the disclosure the 18% one-day drop in the shares is pricing, and it is a bigger event than the redemption number that triggered it.
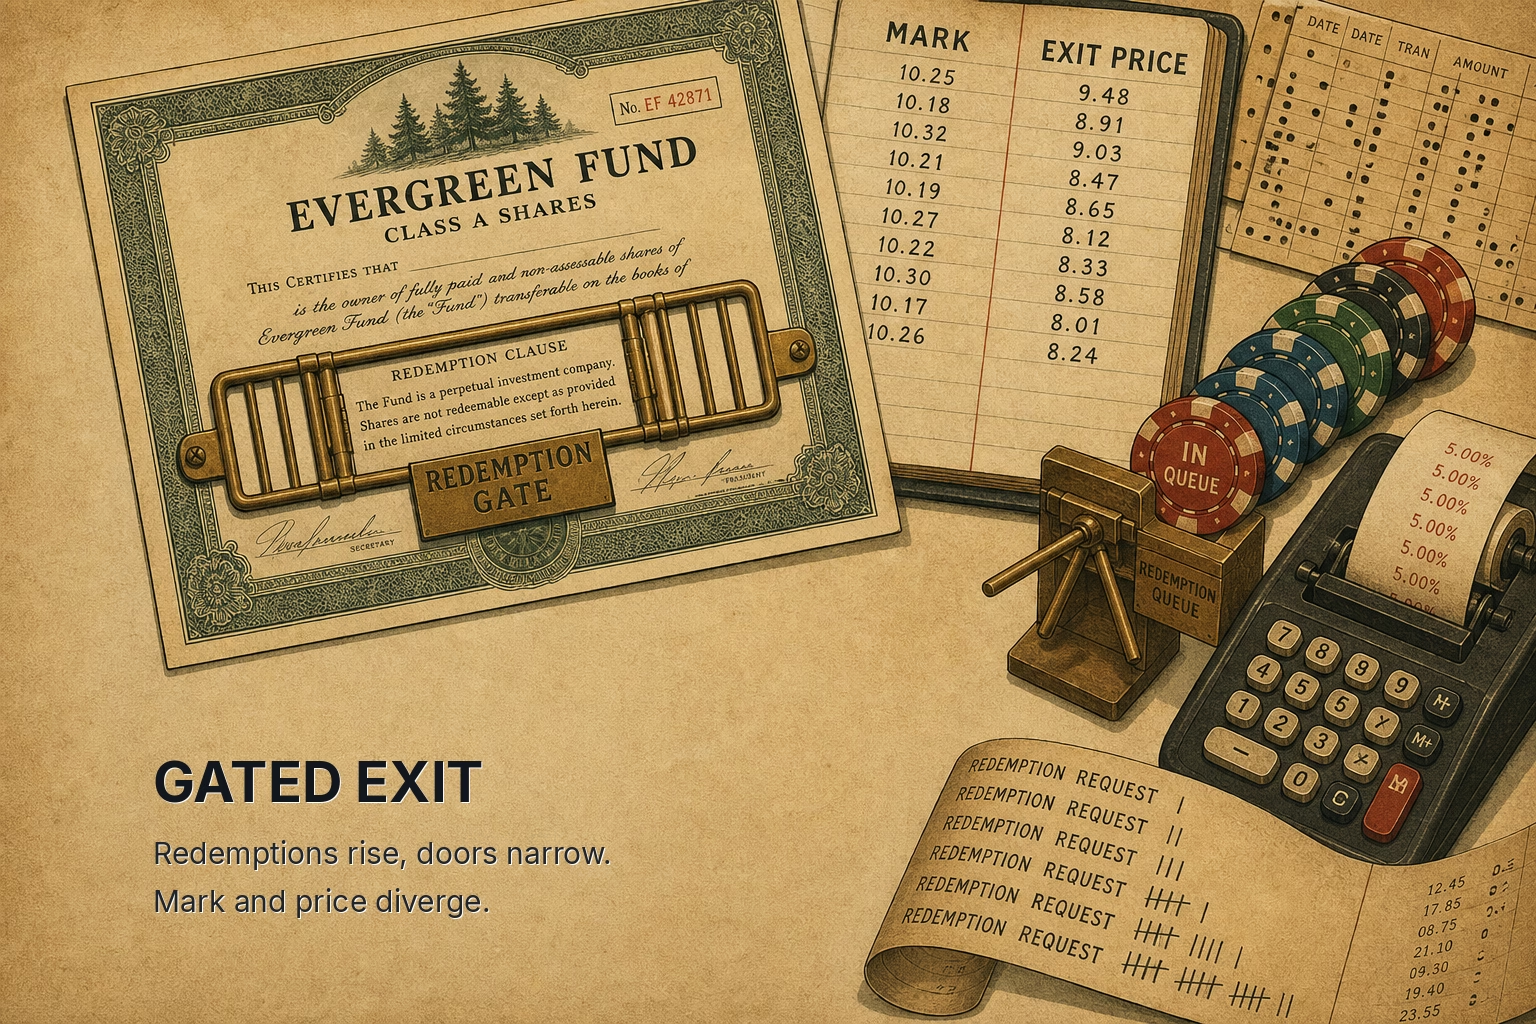
The mechanics are simple enough to state in one line. Withdrawal requests at one of the firm's evergreen private equity funds hit an estimated 9.8% of net asset value in the second quarter, and management responded by capping quarterly redemptions at 5% of NAV. The headline reading is that demand for exits nearly doubled the gate. The reading that matters is what the gate itself certifies: when more than a trivial slice of holders want out at the posted mark, the fund cannot honor that mark at scale. A price that only clears for the first 5% of sellers per quarter is not a price. It is a queue.
What a Gate Actually Discloses
An evergreen fund's entire promise is that private assets, which are illiquid by construction, can be wrapped in a vehicle that behaves like something more liquid. The net asset value is struck from internal valuation marks, not from transactions. For years that arrangement is untested, because inflows exceed outflows and the marks are never forced to meet a bid. Redemptions are paid from new subscriptions and cash buffers, and the valuation is, in effect, self-referential.
The gate is the moment the arrangement gets tested and fails the test. Capping withdrawals at 5% per quarter is management telling holders that the NAV is real only for a small minority of them at any given time. Everyone else is marked at a number they cannot transact at. That is not a technicality. It is the difference between an accounting valuation and a market valuation, disclosed in the one form that cannot be spun: a limit on your right to leave.
We wrote critically about this firm on April 29, 2026, detailing concerns about the valuation marks in its prominent evergreen funds. The concern then was that the marks were being held above what a clearing price would support. The gate is that concern made observable. You do not restrict redemptions to 5% of a value you are confident is transactable.
The Mechanism From Mark to Share Price
The market's 18% repricing of the equity is not a reaction to one fund's liquidity. It is a re-rating of the franchise's fee base and its credibility. Evergreen vehicles are the growth engine that alternative managers have sold to public shareholders precisely because they promise permanent, fee-generating capital that does not run. A gate breaks that promise in front of the whole distribution channel.
The transmission runs in three steps. First, gating one fund tells holders of every other evergreen vehicle in the complex that the exit door is narrower than they believed, which raises the probability of pre-emptive redemption requests elsewhere. Second, the wealth-management platforms that distribute these products to private clients now have a live example of a gate to explain, which slows new subscriptions, the very inflows that let the marks stay untested. Third, if inflows slow while redemption pressure persists, the fund faces the choice it was designed never to face: sell assets into the secondary market at whatever bid exists, which prints a real price against the internal mark.
Each step compounds the last. The equity is not down because one fund is illiquid. It is down because the mechanism that let the marks avoid a market test has visibly weakened across the platform.
The Case That This Is Contained
The strongest counterargument deserves a fair hearing. Redemption gates are a designed feature of these structures, disclosed in the offering documents, and using one is arguably responsible fund management rather than distress. A 9.8% quarterly request rate is elevated but not catastrophic, and a firm with a large balance sheet and diversified fee streams can absorb a single fund's stress without impairing the enterprise. On this reading, the 18% drop is a sentiment overshoot on a governance action that worked exactly as intended.
That case has real merit and it is the reason the stock did not fall further. But it rests on one assumption that the gate itself calls into question: that the marks are approximately right and the liquidity mismatch is merely a timing problem. If the marks are approximately right, gating is prudent and temporary, and subscriptions resume once volatility passes. If the marks are held above a clearing price, the gate is not managing a timing mismatch, it is deferring a valuation reckoning, and every quarter of deferral raises the size of the eventual adjustment.
The distinction is not rhetorical, and it is resolvable by evidence. What settles it is whether any assets in these funds transact at or near their carried value in the coming quarters, or whether transactions, when they occur, print below the mark.
Where the Evidence Would Turn
The read here is that the gate is a valuation signal wearing liquidity clothing. The condition that would confirm it is a widening gap between realized transaction prices and carried NAV as the firm meets redemption demand: secondary sales, asset disposals, or any forced clearing event that prints a number below the mark. The condition that would break it is the opposite, orderly subscriptions resuming while gated redemptions clear at NAV without asset sales, which would vindicate the "prudent timing tool" interpretation.
Two further observables are worth tracking closely. The first is whether redemption requests appear at the firm's other evergreen vehicles next quarter, which would confirm the contagion mechanism across the platform rather than an isolated fund event. The second is the tone of the distribution partners, because the subscription flow that keeps the marks untested is entirely in their hands.
The precise fund-level valuation detail is not something we can reconstruct from public disclosure with confidence, and we are not asserting a specific impairment figure. The direction, though, is set by the action itself. A firm that was confident its marks were transactable would not need to cap the right to transact.
Until a real price meets these marks, the gate is the cleanest evidence available that the two numbers, the stated NAV and the exit value, were never the same. The equity has started to price that gap. Whether it has priced enough depends on what the first forced sale reveals.