The number that matters in the Guggenheim story is not the $2.15 billion price tag on the Dodgers. It is 42 percent. That is the share of Delaware Life'...
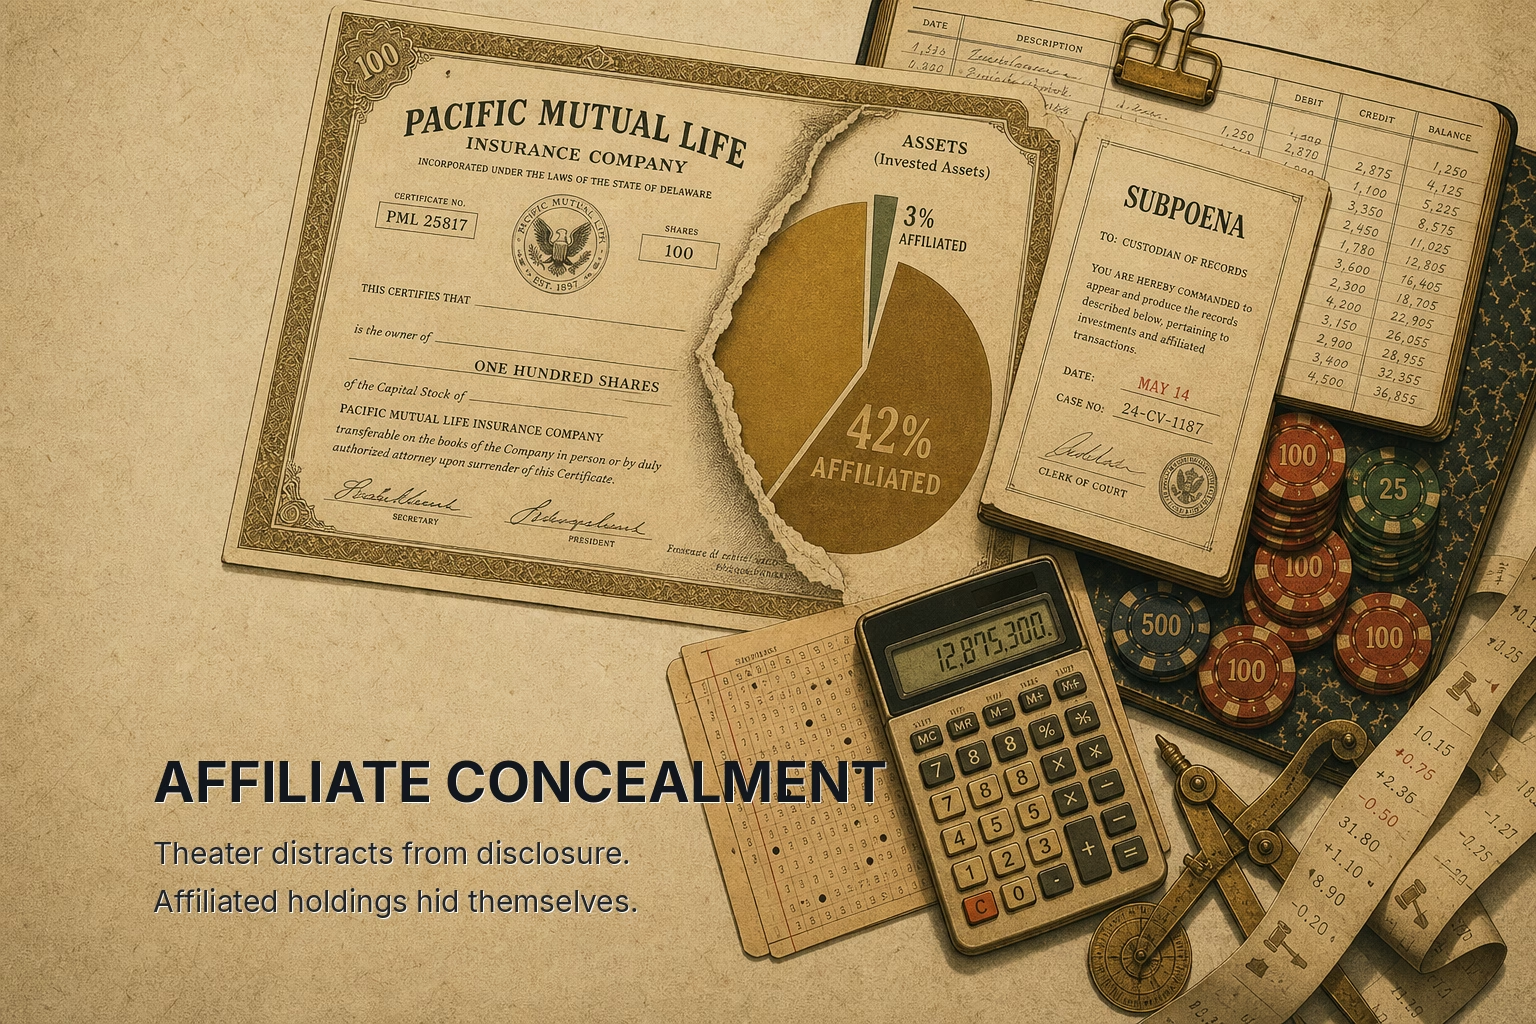
The number that matters in the Guggenheim story is not the $2.15 billion price tag on the Dodgers. It is 42 percent. That is the share of Delaware Life's invested assets that turned out to be tied to Guggenheim-linked borrowers once the company went back through its own books, up from a reported 3 percent. A life insurer does not misplace a category that large by accident of bookkeeping. It misplaces it because the disclosure regime and the economic reality had drifted apart, and nobody with an incentive to reconcile them did so until a grand jury subpoena forced the exercise.
That gap, between what the filings said and what the portfolio actually held, is the whole case. The celebrity ownership stakes are the distraction the reader is meant to fixate on.
The Cash Machine, Read Literally
The class action language, "Guggenheim has essentially operated the Guggenheim Insurers like a cash machine," is rhetorical, but the mechanism it describes is not. An annuity is a long-dated liability. The policyholder hands over a premium today, in Clarice Whitmore's case roughly $45,000, in exchange for a contractual promise to pay decades out. The insurer invests the float against that promise. In an arms-length world, the insurer buys assets whose risk and liquidity are matched to the liability and whose pricing was set by someone with no stake in the insurer.
The allegation is that Guggenheim collapsed both halves of that arrangement. The assets were not independent, they were debt issued by companies linked to the same people who controlled the insurer. And the counterparties who supposedly diffused the risk, the reinsurers, were the other insurance companies in the same group, plus a fifth that was not classified as an affiliate but behaved as one. The complaint puts the intra-group debt at $5.1 billion, the loans to Guggenheim business associates at nearly $1 billion, against a reported surplus of roughly $2 billion.
A single illiquid position inside a diversified, regulated book is defensible. Whitmore's lawyers effectively conceded that when they let the "highly speculative and exceptionally illiquid" framing of the Dodgers loan carry no legal weight on its own. The case they actually built was structural: a closed loop in which the insurer funded entities controlled by its owner, then reinsured the resulting risk with entities also controlled by its owner, and reported the combined arrangement to regulators as diversified financial strength.
Why the Restatement Is the Signal, Not the Suit
The 2013 suit is analytically weak evidence for one reason: it was voluntarily dismissed the day after it was filed. A complaint that vanishes in twenty-four hours proves an allegation was made, not that it was true. On its own it is noise.
What converts the allegation into a hard fact is the 2025 restatement. Delaware Life and Clear Spring Life received grand jury subpoenas over whether certain private credit positions should have been treated as related-party transactions. The response to a subpoena is not a lawyer's characterization, it is a forced re-examination of the books. And the re-examination surfaced roughly $22 billion in private credit deals that had not been disclosed to regulators as flowing, ultimately, to Guggenheim-linked borrowers.
The move from 3 percent affiliated exposure to 42 percent at Delaware Life is the disclosure the market was not pricing. The consensus read of a private-credit-heavy life insurer is that the affiliation is manageable and disclosed. A fourteen-fold restatement says the affiliation was neither measured nor disclosed at the level that mattered, and that the true figure only emerged under legal compulsion. The number the guidance narrative anchored to was wrong by more than an order of magnitude.
This is the recurring pattern in insurance affiliation disputes, and it is worth watching rather than treating as a law: the structure that looks like diversification on the surface is frequently a single credit exposure wearing several disguises. Reinsurance that stays inside the family does not transfer risk, it relabels it. Debt bought from a related issuer does not diversify the book, it concentrates it on the fortunes of the sponsor. History supplies exceptions, and not every affiliated arrangement is abusive, but the direction of a restatement this large is hard to read benignly.
What the Remediation Admits
Mark Walter's response is more revealing than his denial. "There is no victim here," he contends, while simultaneously executing a remediation plan that only makes sense if the exposure was real and material.
He has presented the Delaware Department of Insurance a plan to reduce affiliated exposures. He has already swapped $6.5 billion of Delaware Life's related-party investments for an equivalent amount of assets classified as independent. He has agreed to sell his majority stake in the Los Angeles Lakers and is in talks to sell his stake in Chelsea FC.
You do not swap $6.5 billion of assets to fix a problem that does not exist. The remediation is the confession. The Lakers and Chelsea sales are being read, in the celebrity-owner frame, as a rich man trimming his trophy collection. The equity-fundamental read is different: these are the highly illiquid, sponsor-linked positions that a regulator would most want off an insurer's balance sheet, and the sales are the mechanics of converting a related-party book into something that can pass an arms-length test. The trophies were always partly balance-sheet assets. Selling them is portfolio de-risking dressed as personal restraint.
The Case Against the Case
The strongest counterargument deserves a fair hearing. Related-party investment by insurers is legal, disclosed regularly, and common. Many large insurers run affiliated asset managers precisely so the float can be invested by people who understand the liabilities. Apollo and Athene, KKR and Global Atlantic, Blackstone across several carriers, all operate versions of the insurer-plus-manager structure without scandal. A 42 percent affiliated figure at a single subsidiary is not, by itself, proof of abuse. It is proof of concentration, and concentration is a risk parameter, not a crime.
There is also a genuine defense on the reinsurance point that the complaint underplays. Intra-group reinsurance is a standard capital-management tool. Ceding risk to an affiliated reinsurer, often offshore, is how large groups optimize regulatory capital across jurisdictions. The line between legitimate group capital management and "circumventing the world of legitimate, arms'-length reinsurance" is a real line, but it is drawn by regulators on facts, not by plaintiffs' adjectives.
So the honest position is this. The affiliation itself does not break the thesis. What breaks the benign reading is the restatement's size and its trigger. An insurer that discloses 42 percent affiliated exposure up front is running a concentrated, transparent book that a policyholder can evaluate. An insurer that reports 3 percent and only finds the other 39 after a grand jury asks has a disclosure problem regardless of whether any individual position was sound. The victim question and the disclosure question are separate, and Walter is answering the first while the investigation is asking the second.
What Would Confirm or Break the Read
The observable condition is the Delaware regulator's disposition, not the criminal outcome. If the Department of Insurance accepts the remediation, treats the restatement as a disclosure lapse cured by the asset swaps, and the affiliated ratio settles into a range the carrier can defend as diversified, then the benign reading holds and the whole episode compresses into a governance footnote. Watch the affiliated-exposure percentage after the swaps clear: the number that fell from 42 with the first $6.5 billion is the single cleanest gauge of whether the book is genuinely being de-risked or merely re-labeled again.
The thesis breaks the other way if the grand jury reaches beyond disclosure into the valuation of the affiliated credit itself, because a related-party loan is only as good as the price it was booked at, and a captive lender has every incentive to book it rich. If the investigation establishes that the $22 billion was not merely mis-disclosed but mis-marked, the surplus that supports every annuity in the group is overstated, and the "no victim" claim collapses on contact with a mark-to-market.
Whitmore paid $45,000 for a promise. Whether that promise is fully funded does not turn on who owns the Dodgers. It turns on whether 42 percent was the floor of the affiliation or the first honest number in a series that has further to run.