In September 2008, the credit default swaps written on Lehman Brothers were pricing distress weeks before the ratings agencies moved. Lehman still carri...
Yet the cost of insuring its debt had already blown out to levels that implied a near-certain default. The rating said one thing; the spread screamed another. Anyone reading only the rating was reading yesterday's news.
That gap between the two is the whole point of understanding what a CDS spread actually measures. It is not a rating. It is a price, set by supply and demand for protection, and that price moves for reasons that have as much to do with who is forced to trade as with the borrower's underlying health.
What a credit default swap actually is
A credit default swap (CDS) is a contract that transfers the risk of a borrower defaulting from one party to another. The buyer of protection pays a regular premium, quoted in basis points per year on the amount of debt being insured. In exchange, if the borrower experiences a defined credit event, meaning a default, a bankruptcy, or a failure to pay, the seller of protection compensates the buyer for the loss.
The premium the buyer pays is the CDS spread. If a five-year CDS on a company trades at 200 basis points, insuring $10 million of that company's debt costs $200,000 per year. The number sounds like a straightforward measure of default risk, and in a textbook it is.
The practical implication is that the spread is not published by a committee or filed with a regulator. It is a market clearing price, and market clearing prices carry information that slower measures like ratings cannot.
What the spread is supposed to price
In the clean version of the theory, a CDS spread compensates the seller for the expected loss from default. That expected loss has two parts.
The first is the probability that the borrower defaults over the life of the contract. The second is the loss given default, meaning how much of the debt's value is actually lost after recovery. A defaulted bond that recovers 40 cents on the dollar has a loss given default of 60%.
Put those together and you get the core relationship. Annual spread ≈ default probability × loss given default. Rearranged, the spread implies a default probability once you assume a recovery rate.
Assume a 40% recovery, so loss given default is 60%. A spread of 300 basis points, or 3%, implies an annual default probability of roughly 3% ÷ 0.60 = 5%. That is the arithmetic every credit desk runs before breakfast.
The practical implication is that you can back out the market's implied default probability from any quoted spread, provided you fix a recovery assumption. But the arithmetic only explains the spread when protection changes hands in an orderly market. It does not explain what happened to Lehman, and it does not explain the moments that matter most.
Why the spread prices more than the borrower
Here is what the clean formula leaves out. A CDS spread also prices who is forced to buy protection, when they are forced to buy it, and whether the sellers have the balance sheet to keep writing it.
Protection sellers are overwhelmingly dealers and a handful of large financial institutions. When they sell protection, they take on default risk, and they hedge that risk, often by shorting the borrower's bonds or by buying offsetting protection elsewhere. Their willingness to keep selling depends on their own capital, their own risk limits, and the price of their hedges.
When the borrower's outlook deteriorates, three things happen at once. Buyers of protection rush in. Sellers pull back because their existing positions are already losing money and their risk limits are tightening. And the dealers who intermediate the market widen their quotes to protect their own balance sheets. The spread gaps not because the default probability doubled overnight, but because the supply of protection collapsed while demand spiked.
This is the flow mechanism that consensus misses when it reads the spread as a pure default forecast. The tape moves because someone is trapped. A fund that sold protection and is now facing margin calls must either post collateral or unwind, and unwinding means buying back protection into a market where sellers have vanished. That forced buying pushes the spread wider, which triggers more margin calls, which forces more buying. The loop feeds itself.
Lehman's CDS did not blow out because the market suddenly recalculated a fundamental default probability. It blew out because everyone who had sold Lehman protection wanted out at the same moment, and there was no one left to take the other side at the old price. The spread became a measure of positioning stress, not of credit fundamentals.
The practical implication is that when you see a spread gap violently, your first question should not be "what changed about the borrower." It should be "who is forced to trade, and in which direction." The fundamentals often catch up to the spread only later, once the ratings agencies and the analysts have processed what the flow already knew.
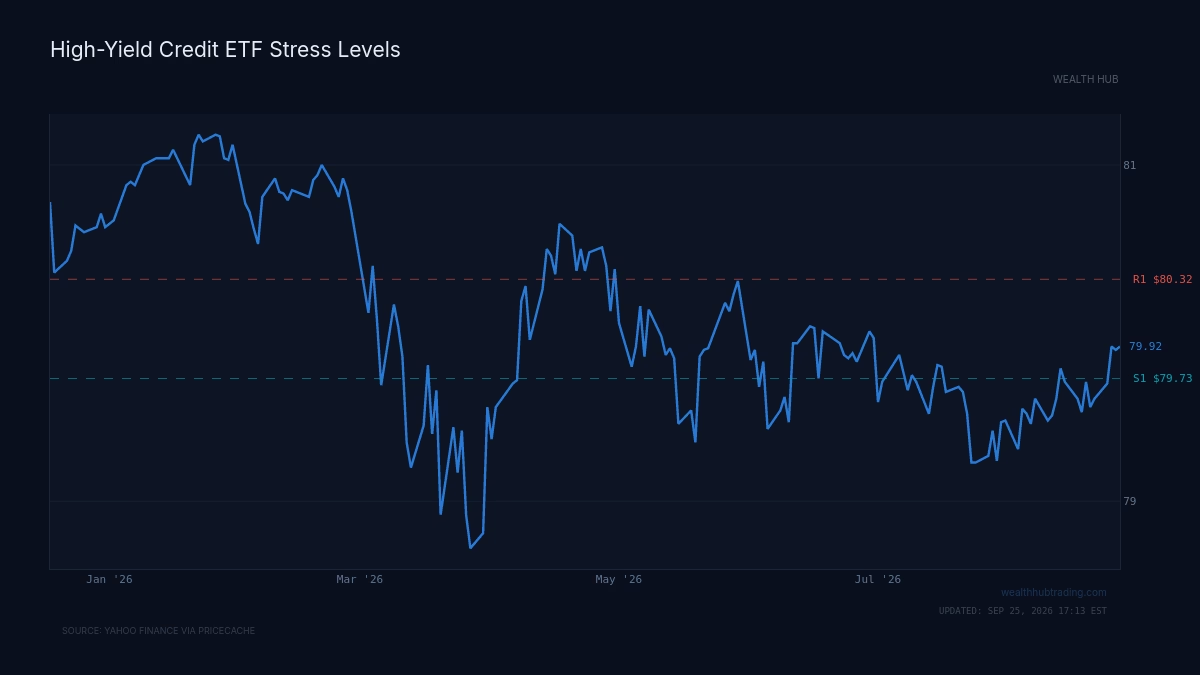
Why spreads move before ratings
Ratings are backward-looking by construction. A rating agency reviews financials, meets management, and updates a rating on a schedule measured in quarters. The process is deliberate, and deliberation is slow.
A CDS spread updates continuously. It aggregates the views and the forced actions of every participant in real time. When a hedge fund with a large protection-selling position starts to unwind, that shows up in the spread the same day. It shows up in the rating months later, if at all.
This is why spreads gap before ratings ever move, and it is the single most useful property of the CDS market for someone trying to read distress early. The 2008 episode is the canonical example, but the pattern recurs. In the European sovereign crisis of 2011 and 2012, the CDS on peripheral government debt widened well ahead of the formal downgrades. In corporate distress cycles, the CDS on a struggling issuer routinely prices a default that the rating still denies.
The practical implication is that the spread and the rating carry different information at different speeds. The rating tells you what a slow, careful process concluded last quarter. The spread tells you what the fastest, most capital-constrained participants are doing right now.
When the flow read fails
The flow interpretation is powerful, but it is not universal, and treating it as a law will cost you.
Sometimes a spread widens for exactly the reason the textbook says: the borrower genuinely deteriorated and the market repriced default risk in an orderly way. There was no forced seller, no margin cascade, no positioning stress. Reading that move as a flow event would lead you to fade a repricing that deserved to stick.
The mechanism also breaks when liquidity is thin. A CDS on a name that barely trades can gap on a single transaction, and that gap tells you almost nothing about either fundamentals or aggregate positioning. It tells you one participant needed to trade and found no depth. The spread is real, but it is not informative in the way a liquid name's spread is informative.
And the loss-given-default assumption embedded in every implied-probability calculation can be badly wrong. In the 2008 financial crisis, recovery rates on some senior financial debt came in far below the 40% convention, which meant spreads that looked like they priced a modest default probability were actually consistent with a much higher one once the true recovery was known. The arithmetic is only as good as its recovery assumption.
The practical implication is that you must diagnose the move before you interpret it. Ask whether the spread widened on heavy protection demand into vanishing supply, which points to flow, or on a genuine fundamental catalyst into an orderly market, which points to repricing. The two look identical on a spread chart and mean opposite things for what happens next.
What this means for reading credit
A CDS spread is a live price for insurance, and like any insurance price it reflects both the risk being insured and the condition of the people writing the policy. Most of the time those two move together and the spread reads like a clean default forecast. In the moments that matter, when a large seller is forced to become a buyer, the spread decouples from fundamentals and becomes a readout of positioning stress instead.
Read the spread against the rating to catch distress early, because the spread updates in real time and the rating updates on a calendar. But read the spread against the flow to know what the move actually means, because a gap driven by forced buying resolves differently from a gap driven by genuine deterioration. The number on the screen is not the answer. It is the question of who is trapped, and that is the question worth asking first.