On May 6, 2010, at 2:45 in the afternoon, the price of the S&P 500 fell almost 6% in about five minutes, then recovered most of it before three o'clock....
On May 6, 2010, at 2:45 in the afternoon, the price of the S&P 500 fell almost 6% in about five minutes, then recovered most of it before three o'clock. Some blue-chip stocks briefly traded at a penny. Others printed at $100,000. The event became known as the Flash Crash, and the official post-mortem, published by the SEC and the CFTC, kept returning to one word: fragmentation. Orders that could not find a fill on one exchange were routed to another, then another, chasing a national best price across a market that had been legally welded together but physically remained dozens of separate machines in separate buildings.
That welding is Regulation National Market System, adopted by the SEC in 2005 and known as Reg NMS. Understanding what it did, and the one place where intuition about it goes wrong, explains why speed itself became the tradable edge on Wall Street.
What the NBBO actually promises
The centerpiece of Reg NMS is the National Best Bid and Offer, or NBBO. The NBBO is the highest price anyone is publicly willing to pay for a stock (the best bid) paired with the lowest price anyone is publicly willing to sell it for (the best offer), collected across every registered US exchange at a single instant.
The rule that gives the NBBO its force is the Order Protection Rule, sometimes called the trade-through rule. A trade-through happens when a trade executes at a worse price than a quote available somewhere else. Reg NMS makes most trade-throughs illegal for the protected top-of-book quotes. In plain terms: your order must fill at the NBBO or better, and a venue cannot ignore a better price sitting on a competing exchange.
For you as an investor, this is a genuine protection. When you enter a market order to buy 100 shares, you are guaranteed the execution cannot legally happen above the best publicly displayed offer in the entire national market. Before Reg NMS, a slow regional exchange could fill you at an inferior price while a better quote sat untouched elsewhere. That specific abuse is now largely closed.
Where intuition gets it wrong
Here is the place almost everyone misreads the mechanism. The NBBO sounds like a single, continuously accurate price that lives in one place. It is not. The NBBO is a calculation, and every calculation takes time and data to produce.
The best bids and offers are generated on separate exchanges scattered across New Jersey and beyond. Each venue publishes its quotes; a central processor called the Securities Information Processor, or SIP, gathers those feeds, consolidates them, and broadcasts the official NBBO. That gathering and broadcasting is not instantaneous. Light itself takes time to cross a fiber-optic cable, and the SIP adds processing delay on top.
So the official NBBO you see is always a slightly stale photograph of a market that has already moved. The gap between what the SIP reports and what is actually tradable at each exchange right now is the latency seam the rule created without intending to. Reg NMS made the market one price in law while leaving it many machines in physics, and the distance between those two facts is measured in microseconds.
That gap is not a rounding error. It is an asset.
How the seam became the edge
Trace the causal chain and the origin of high-frequency trading falls out of it directly.
First-order effect: Reg NMS required orders to be routed to wherever the best price sits, which fragmented trading across more than a dozen exchanges plus a comparable number of off-exchange venues. No single venue holds all the liquidity anymore, so orders constantly travel between them.
Second-order effect: because the consolidated NBBO from the SIP arrives slightly later than the raw data from each individual exchange, a firm that reads the direct exchange feeds and co-locates its servers inside the exchange's own data center sees price changes before the official NBBO updates. Co-location means renting rack space physically next to the matching engine so the cable run is measured in feet, not miles.
Third-order effect: a firm that sees the price move first can react first. It can post or cancel quotes, or hit a slower participant's resting order, in the window before the public NBBO catches up. The economic value that migrated into that window is the return on being fast. Speed stopped being a convenience and became the product itself.
This is the counterintuitive result. A rule written to guarantee every investor the best price created a measurable time advantage for whoever could read the market faster than the official best-price feed could be assembled. The protection is real, and the seam it opened is also real. Both things are true at once.
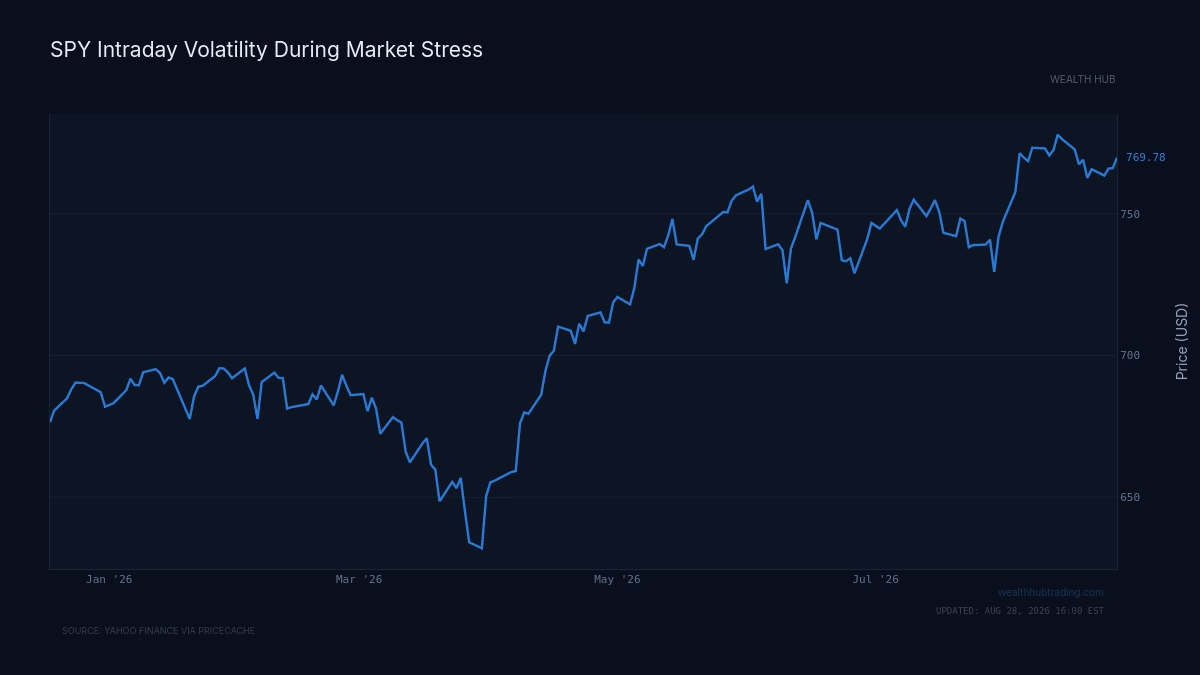
The 2010 Flash Crash was the seam under maximum stress. When a large automated sell program hit a market already thin on buyers, orders cascaded from venue to venue searching for fills the fragmented structure could not supply fast enough. The routing logic worked exactly as designed, and that is precisely why prices detached from any sane value for a few minutes. The mechanism did not fail; the mechanism revealed what it was.
When the mechanism does not behave as advertised
The NBBO protects only displayed, top-of-book quotes on registered exchanges. Several large categories of trading fall outside that protection, and knowing them changes how you interpret your own fills.
Hidden and reserve orders are not protected, because the rule can only shield quotes it can see. Trades inside dark pools, private venues where orders are not publicly displayed, reference the NBBO but do not contribute to setting it. And size beyond the top of book is unprotected: the NBBO guarantees the best price for the shares displayed at that price, not for your entire order. If the best offer shows 100 shares and you buy 5,000, only the first 100 carry the guarantee. The rest walk up the book to worse prices, which is the everyday cost called slippage.
The mechanism also assumes the SIP is functioning. During the most violent moments of the Flash Crash, quote traffic overwhelmed parts of the reporting infrastructure, and the reference price traders were legally chasing was, for stretches, not a reliable description of anything. A protection that depends on a timely consolidated feed is only as good as the feed on its worst day.
What this means for how you trade
The practical implication is specific. Use limit orders, not market orders, for anything beyond small, liquid names. A limit order names the worst price you will accept, which converts the NBBO's stale-photograph problem from your risk into someone else's; you simply do not fill above your limit. A market order accepts whatever the book offers as your order walks it, and in a fast or fragmented moment that price can be materially worse than the NBBO you saw when you clicked.
For a retail-sized order in a heavily traded stock, the latency seam costs you effectively nothing, because your order is smaller than the displayed size and fills at the top of book instantly. The seam matters when your order is large relative to displayed liquidity, when the stock is thinly traded, or when the whole market is moving fast. Those are exactly the conditions under which the difference between the price you saw and the price you got stops being academic.
Reg NMS gave you a legal right to the best displayed price and, in the same stroke, created the microsecond gap where the value of speed now lives; knowing that the NBBO is a calculation rather than a fact is what lets you price your own orders defensively instead of trusting a number that has already aged by the time it reaches your screen.